All Categories
Featured
Understanding 2026 Medicare Benefit Options and Seniors
Understanding How Indexed Universal Life Policies Protect...
Direct Consumer Advice for Selecting 2026 Medicare Plans
Table of Contents
You are paying for permanence and ensured cash value, not simply a death advantage. Larger whole life policies scale up roughly in proportion to the face amount.
Below are normal term life rates for elders a $250,000 10-year term policy (male, non-smoker): AgeMonthly PremiumAnnual Cost60$70$84065$120$1,44070$210$2,52075$380$4,560 Most carriers top term length as you age a 20-year term is widely offered at 60 but rarely at 70. Match the term to a specific need (a remaining mortgage, a spouse's income gap).
A single controlled condition (blood pressure, cholesterol) has a bigger dollar effect at 65 than at 35. An expert broker assists you find the carrier that treats your health most favorably. For a much deeper breakdown, see our devoted guides for life insurance over 50 and life insurance over 60. This is the most affordable time to buy, even if your protection requirements are modest.
Essential Expense and Burial Insurance Options
Lock in the most affordable rate possible for the longest period. You can always add more protection later. Peak buying time. The majority of people start families, purchase homes, and struck their stride in their professions. SituationRecommended CoverageMarried, kids, mortgage$750K-$1.5 MSingle moms and dad$500K-$1MHigh earner ($150K+)$1.5 M-$3MPersonal + essential person coverage 20-year level term if your kids are young.
Many responsibilities are at their peak. Home mortgage is developed, kids are growing, and college is approaching. SituationRecommended CoverageKids heading to college in 5-10 years$500K-$1M (match to remaining years)Big mortgage remainingCoverage matching balanceApproaching peak making years10-15x income 15 or 20-year level term. If you already have a 30-year term from your 30s, you might have enough.

Kids might be independent, mortgage is diminishing, and retirement cost savings are growing. SituationRecommended CoverageMortgage practically paid offReduce protection or keep for income replacementKids independentCoverage need drops significantlySpouse depends on your incomeMatch to years up until retirementFinal expenses only$25K-$50K irreversible policy 10-year term for specific needs, or last expense whole life for long-term coverage.
Obtaining Individual Health Insurance Quotes Online
Here is the real cost of procrastination: Buy at AgeMonthlyTotal Over 20 YearsExtra Cost vs.
And that assumes you stay healthy. What is the finest age to buy life insurance? The finest age is as young as possible.
A 25-year-old pays approximately half what a 35-year-old pays for the exact same coverage. Buying in your 20s locks in the most affordable rate for the longest period. How much does life insurance coverage increase by age? Rates increase about 8-10% per year in your 20s-30s, 10-15% per year in your 40s, and 15-20% annually in your 50s-60s.
PPO vs HMO Health Insurance Options
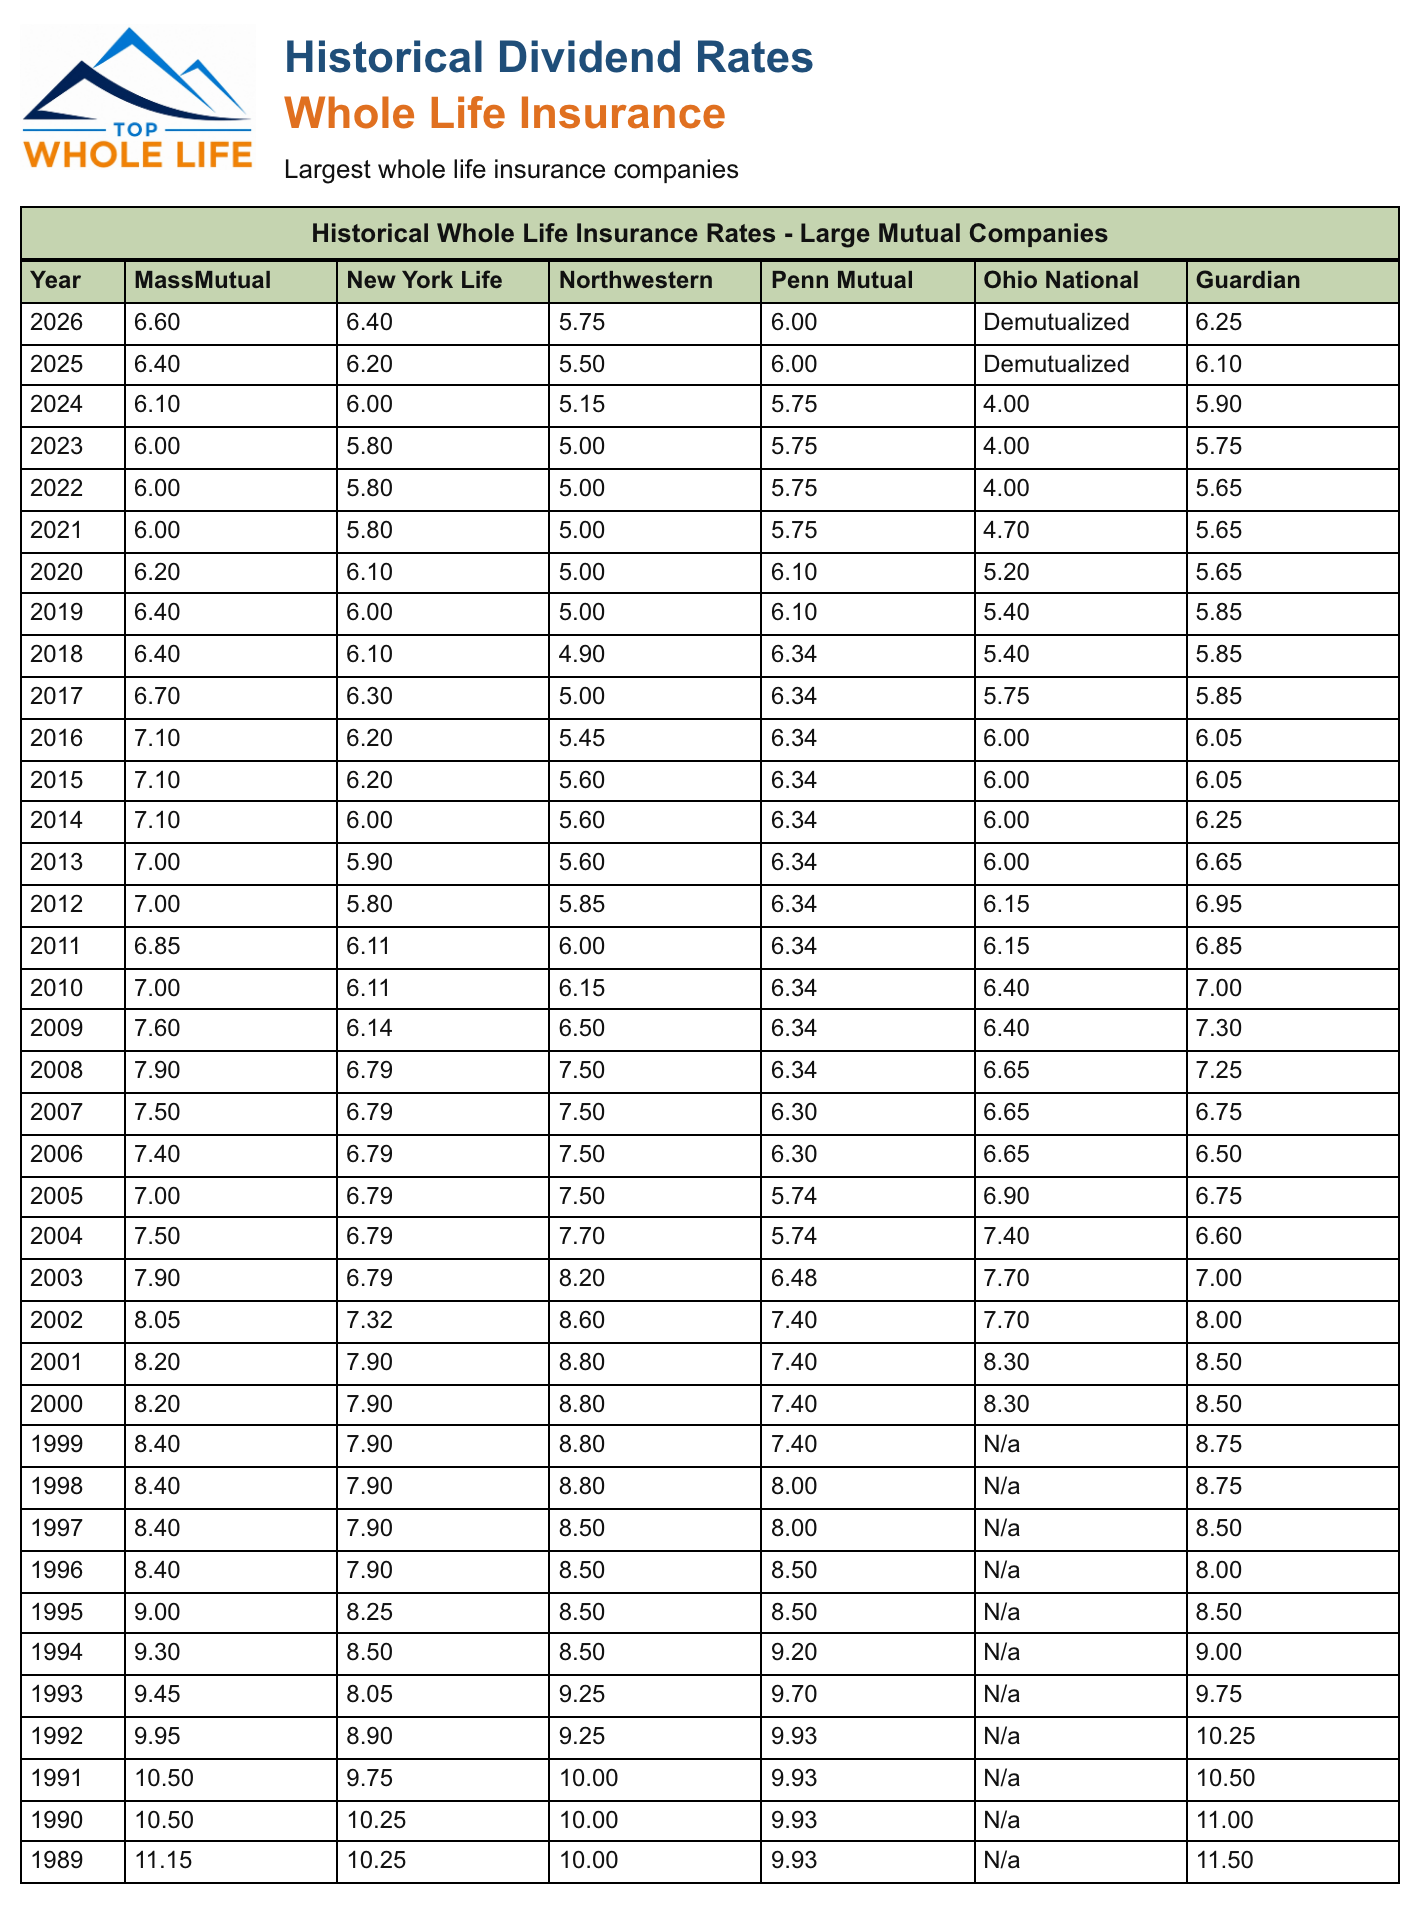
Is it too late to purchase life insurance at 60? What are entire life insurance coverage rates by age? Whole life is a number of times more expensive than term because the protection is long-term and develops cash value.
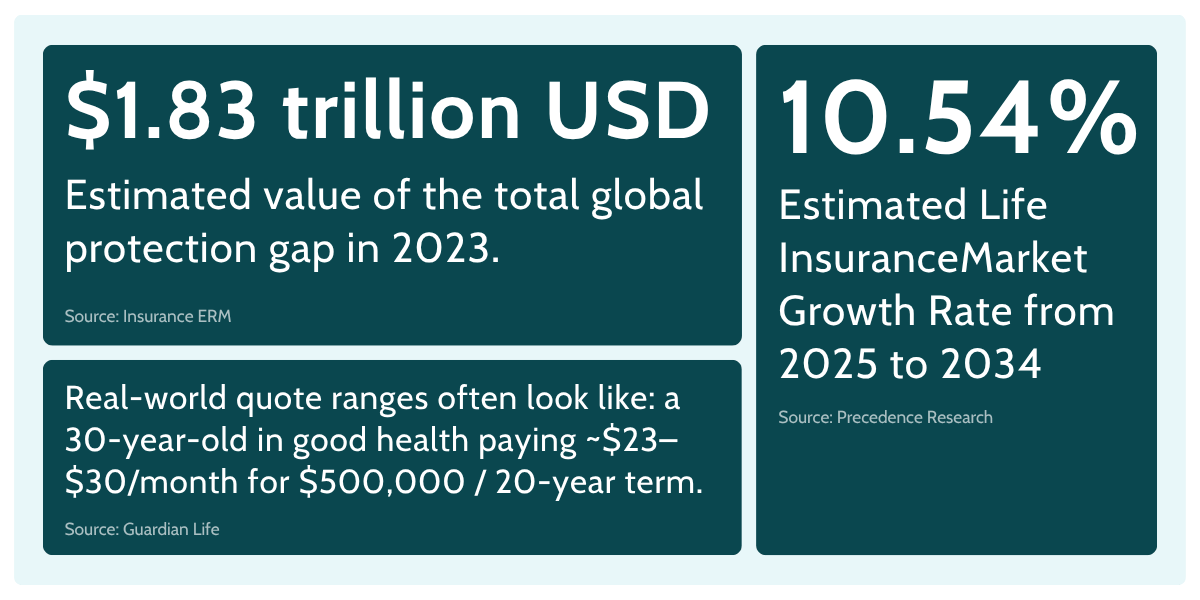
Women pay roughly 10-20% less. Larger entire life policies scale up from there. See the whole life chart below. What are common life insurance coverage rates for senior citizens? For a healthy senior, a $250,000 10-year term policy (male, non-smoker) costs approximately $70/month at age 60, $120/month at age 65, and $210/month at age 70.
Rates increase steeply with age, so applying sooner rather than later matters most in this bracket. Compare rates from leading life insurance coverage providers. In this post, we'll break down the different aspects that influence life insurance expenses, how much you can anticipate to pay, and tips for getting the best rates.
The purchasing a 20-year term policy for $250,000 in coverage. for the exact same protection. looking While the. Term Life insurance is often described by other names, such as "instantaneous life insurance" or "no test life insurance." These terms explain various kinds of term life insurance coverage policies. Life insurance coverage tends to be more pricey than impairment insurance coverage since it provides a death benefit to beneficiaries, which can be a considerable amount of cash.

Latest Posts
Mechanics of Whole Life Insurance to Protect Families

Understanding 2026 Medicare Benefit Options and Seniors

Part D Enrollment Tips for Seniors